
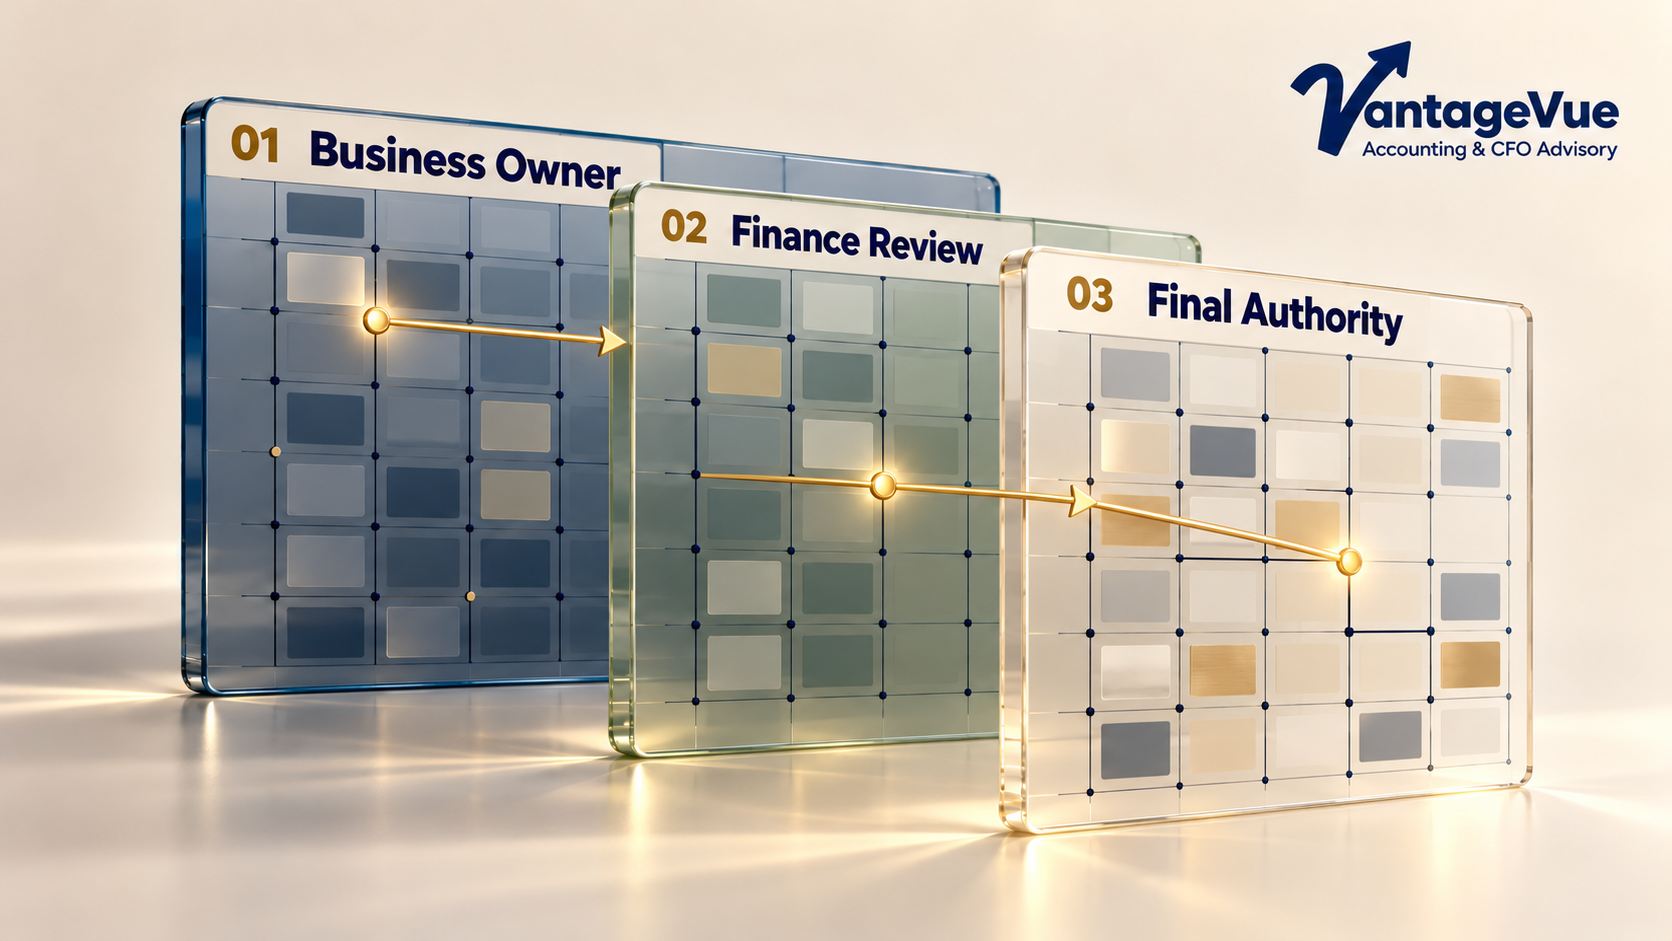
A department lead needs to renew a software subscription before it expires. The expense is in the budget, but the contract runs for another year, and the vendor has changed its payment terms. The lead sends it to the founder, who is traveling. Finance sees the invoice but cannot tell whether the purchase has been approved. A routine decision waits in three inboxes.
The problem is not necessarily the price. It is that the business has never decided who can commit it to an expense, who reviews the financial implications, and who can release the payment.
In a small company, people often resolve those questions by asking the owner. As teams and purchase volumes grow, that habit creates delays and inconsistent decisions. A financial approval matrix puts the rules into writing. It connects approval workflows and internal controls, so routine work can move while material commitments still receive appropriate review.
What a Financial Approval Matrix Needs to Decide
An approval matrix, sometimes called a delegation of authority matrix, should answer more than “Who is the manager?” It should identify:
- What type of commitment is being made;
- Whether it is within an approved budget;
- Its total value and duration, including renewals;
- Who can approve the business need and who must review the financial risk; and
- Who is authorized to sign the agreement or release the payment.
These are related actions, but one approval does not automatically authorize all of them. A department head may confirm that a tool is needed. Finance may confirm that the budget and payment terms have been reviewed. Only a designated signatory may be authorized to bind the company to the contract.
Consider that software renewal again. If the invoice is $2,000 a month under a three-year agreement, the scheduled payments total $72,000. A rule based only on the first invoice misses the larger commitment. The matrix should state whether approval limits apply to a single payment, the annual cost, or the full contract value. It should also say what happens when a renewal increases the price or changes the terms.
Build the Matrix Around Common Decisions
Leadership does not need to catalog every possible purchase before setting useful rules. Start with the decisions that most often cause delays, create obligations, or invite exceptions.
| Decision type | Business owner | Finance review | Approval authority |
| Budgeted expense within a set limit | Confirms need and amount | Checks budget, coding, and support | Named approver within their limit |
| Expense outside budget or above a limit | Explains the business case | Reviews cash effect and alternatives | Executive, or board if authority is reserved |
| New contract or material renewal | Confirms scope and benefit | Reviews full commitment and payment terms | Authorized contract signatory |
| New vendor or changed bank details | Confirms the relationship | Independently verifies identity or instructions | Designated setup or change approver |
| Urgent exception | Documents the urgency | Records completed and outstanding checks | Named backup or executive approver |
Illustrative structure only. Each company should set its own monetary limits, signatory powers, reserved decisions, and review roles under its governing documents and policies.
A financial approval matrix becomes more useful when each row also specifies the evidence required. A purchase request might need the quote, budget code, contract term, and business owner. A bank-detail change needs an independent verification record. Without that information, even the correct approver has to guess what has been checked. Approval of a commitment should not, by itself, grant access to release its payment.
Separate Requesting, Approving, and Paying
A signature on an invoice can mean several different things. One person may be confirming receipt of a service. Another may be authorizing a commercial commitment. Someone in accounts payable may be checking that the invoice matches the agreement. A payment approver authorizes cash to leave the bank.
Those steps should be named rather than collapsed into one “approved” status.
Smaller teams may not have a different employee for every task. In that case, leadership can choose a compensating review, such as a second person checking the vendor change or the owner reviewing a payment report after release. The point is to understand where one person could initiate, alter, and pay the same transaction without independent visibility.
For a growing business, a practical approval process should protect the payment process while allowing routine decisions to move on time.
The role of a controller often includes maintaining accounting controls and supervising transaction processing. That does not mean the controller should make every commercial decision. The business owner remains accountable for the need; financial leadership helps assess the commitment and define an appropriate route for approval.
Give Exceptions an Actual Route
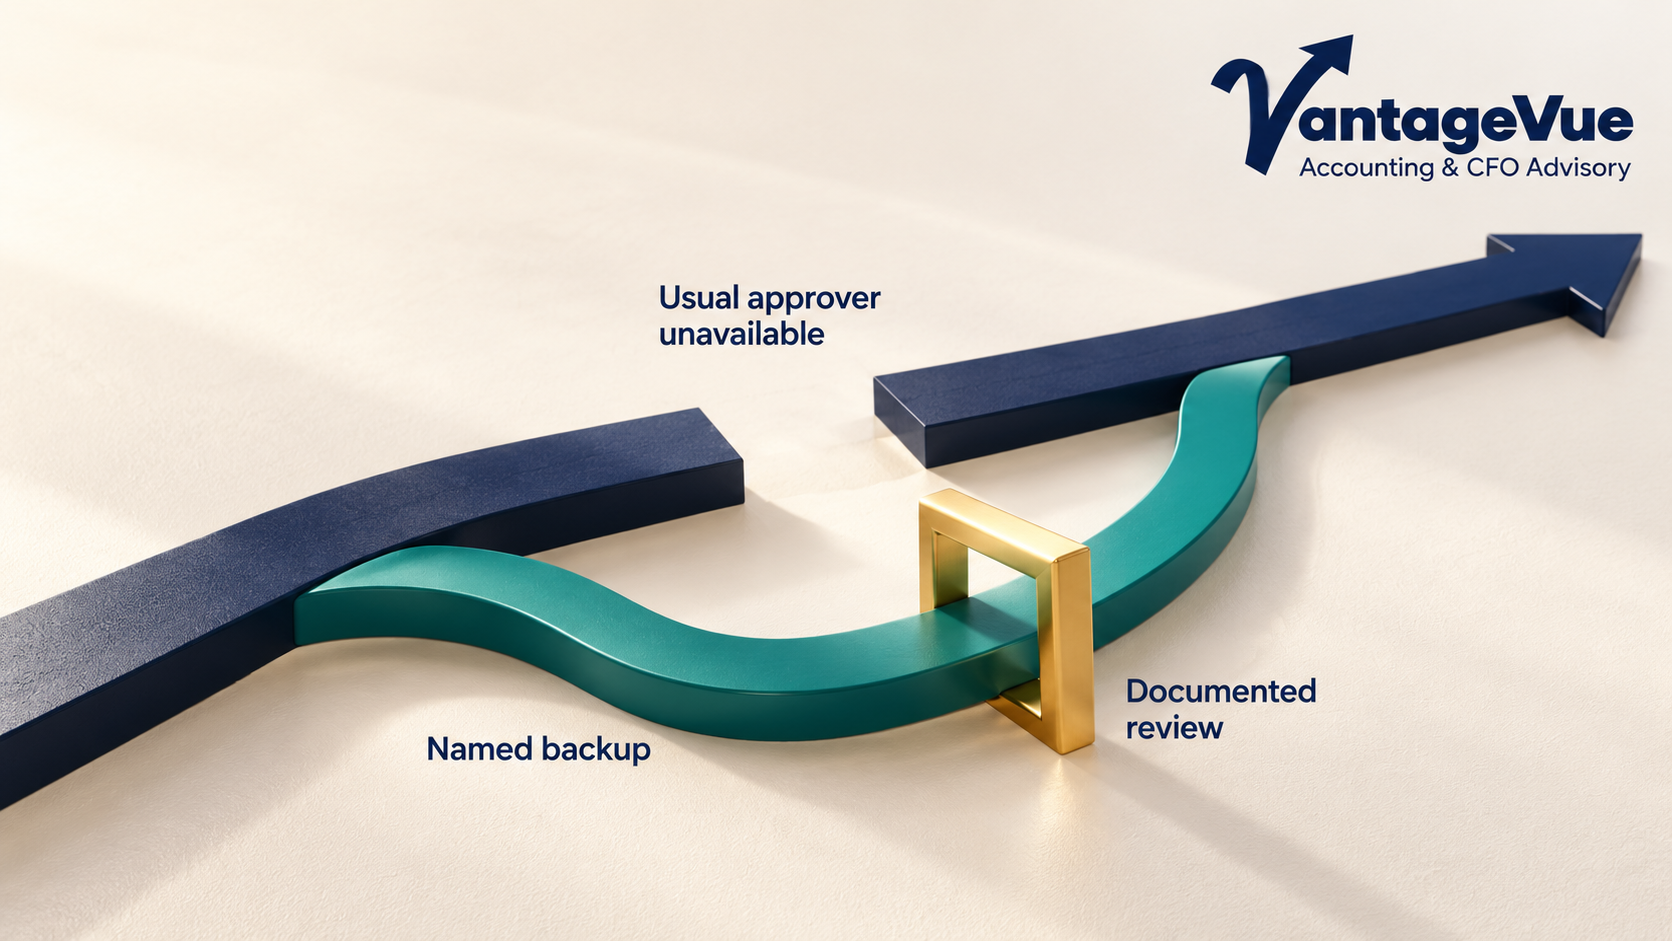
A financial approval matrix that only works when the founder is available will quickly be bypassed. Vacations, urgent repairs, customer deadlines, and unexpected vendor issues are normal operating conditions.
Define a backup approver in advance. State which decisions can be delegated, for how long, and whether the substitute can approve a request made by someone in their own reporting line. If an urgent payment must proceed before a normal review, record who authorized it, why it was urgent, what checks were completed, and who will review it afterward.
An exception should be visible as an exception. Quietly changing a purchase date, splitting one commitment into smaller invoices, or treating a new contract as a routine renewal defeats the policy. If the same exception appears repeatedly, leadership should examine the underlying rule. The limit may be too low, the assigned approver may be unavailable, or the budget may no longer reflect how the business operates.
Test the Rules Against Real Transactions
Before putting your financial approval matrix into a finance system, take a small sample of recent decisions: a recurring subscription, equipment for a new hire, an urgent vendor payment, a contract renewal, and a proposed purchase outside the budget.
For each one, ask where the request begins, what information the approver receives, who can commit the company, and how finance knows approval was granted. Then identify any transaction that had no clear owner or required the founder’s informal permission despite being routine.
This exercise helps set approval limits based on the company’s actual transaction sizes and risk, rather than copying another organization’s numbers. It also reveals whether the annual budget and the approval matrix agree. A budget authorizes a plan for spending; the matrix identifies who can approve individual commitments under that plan.
Once those rules are clear, a system can route requests and preserve an audit trail. Our guide to evaluating an ERP contract discusses testing approval limits, user permissions, and controls before committing to a platform. Software can enforce a defined rule, but it cannot settle a policy disagreement the leadership team has left unresolved.
Keep the Policy Current as the Business Changes
A financial approval matrix should have an owner and a review date. A new department, another legal entity, a larger purchasing volume, or a change in banking authority can make yesterday’s rules unreliable. Finance can review exceptions and bottlenecks with leadership each month, then propose changes where the pattern warrants them.
A useful review is brief and specific: Which requests waited too long? Which requests were approved without the required support? Did any contract create a larger obligation than its invoice suggested? Did backup authority work when someone was absent?
The goal is a decision process people can follow on an ordinary Tuesday. Routine expenses should have a clear path. Significant commitments should reach the people responsible for the risk. And finance should be able to show how the decision was made after the invoice has been paid.
VantageVue helps growing businesses define financial responsibilities, design workable approval processes, and connect those rules to accounting and reporting workflows. Fractional CFO guidance can help leadership set decision boundaries while the finance team puts them into practice.
To discuss how VantageVue can help design approval rules that fit your business, visit our Systems & Workflows services or contact us:
(612) 200-2651